
Case Studies
How a Biopharma Company Eliminated 30,000+ Manual Hours and Reduced Supply Chain Communication Latency by 60%
Read More
Deposit fraud losses at US regional banks are primarily detection and investigation problems. Most banks have the data; what they lack is the process architecture to turn that data into precise, fast, low-friction decisions. This case study documents how a leading American full-service bank addressed that gap. In a two-year engagement, Altimetrik supported the bank’s redesign of fraud operations policy and procedure, alert category enhancement, resulting in a 57% reduction in operational losses, a 43% reduction in false positives, and a 50% reduction in customers experiencing unnecessary deposit holds.
A leading US-based, full-service provider of consumer and commercial banking, wealth management, and mortgage products and services. The bank serves customers throughout the South and Midwest, including Texas.
When Altimetrik began working with the bank, its deposit fraud operation had a structural challenge. Every suspicious transaction, regardless of risk level, check type, or dollar value, entered the same manual investigation queue. There was no prioritization based on risk category, and no direct hold for clear-cut cases.
The consequence was predictable. Investigators spent most of their time on alerts that led nowhere:
The engagement began with a structured diagnostic mapping of how fraud manifested across deposit types, where investigator decisions were made, and which process steps needed automation. After the diagnostics, we adopted a three-pronged approach and implemented the following:
Intelligent Process Design
Data & Analytics
Targeted Automation
Operational Efficiency
Quality & Compliance
Customer Experience
Our customer’s story is not unique. According to the Nasdaq 2026 Global Financial Crime Report, false-positive alerts consume 27% of anti-financial-crime team hours on average and more than 40% at one in five institutions. Check fraud in the US is growing at 28% annually. Most fraud operations were not built for this environment.
Three places to start
What’s driving the surge in deposit and check fraud at regional banks right now?
Check fraud in the US is growing at 28% annually (Nasdaq 2026 Global Financial Crime Report), and most fraud operations were built for a different threat environment. Regional banks are particularly exposed because they often rely on undifferentiated investigation queues — every suspicious transaction, regardless of risk level or dollar value, gets treated the same way. That structural problem means investigators spend most of their time on alerts that lead nowhere, while genuinely high-risk activity moves at the same pace as low-risk noise.
How do I know whether our fraud detection model is calibrated or just generating volume?
The clearest diagnostic is your alert-to-fraud conversion rate — the share of alerts that ultimately confirm fraud. If you don’t have that number readily available, that gap itself is worth addressing first. A second useful signal: audit how investigator time is actually spent. If more time goes to alerts that clear than to confirmed fraud, the constraint is process design, not the team.
How do banks balance tighter fraud controls with not penalizing good customers?
This is the core tension in fraud operations, and it’s mostly resolved through segmentation. Not every alert warrants the same response. A hold prioritization matrix that differentiates by check type, deposit mode, and dollar value lets you apply straight-through holds only where the risk clearly justifies it, and route lower-confidence cases to senior review. The goal is to calibrate the hold-to-fraud ratio, reducing unnecessary holds without loosening controls on genuinely high-risk transactions.
What’s Altimetrik’s footprint in financial services, and what does the team cover?
Altimetrik works with five of the top ten US regional banks, seven Tier-1 global banking institutions, and five global payment leaders. It has over 20 years of experience in financial crime operations. Coverage spans the full stack: deposit, check, and bank card fraud investigation; dispute, claims, and reconciliation; case management and SAR pre-file; KYC (CDD and EDD); transaction monitoring and currency reporting; and AML investigation. The team also has hands-on delivery experience across the major platforms, such as Actimize, Verafin, Palantir, Detica, FCMS, LexisNexis, and IDology.
Who leads the fraud operations at Altimetrik?
Altimetrik’s financial crime operations practice is led by practitioners with deep banking backgrounds. Somesh Auddy (VP, Digital Operations) brings 25+ years of global delivery experience. Vanishri Balnad and Girisha Aithala, both GMs in Digital Operations, each have 20+ years in banking delivery and operations transformation, respectively. The people running the engagement have seen these problems across multiple institutions and regulatory environments.
Learn more about Altimetrik’s regional banking capabilities here
A leading global chemical producer wanted to generate additional revenue from its top 25 customers. However, account managers lacked visibility into more than one million products distributed across approximately 20 planning units, limiting their ability to identify relevant cross-sell and upsell opportunities.
Altimetrik created a Single Source of Truth that unified product, customer, sales, and market data. Machine learning algorithms analyzed this information alongside geographic restrictions and customer spending capacity, generating actionable recommendations through an intuitive dashboard.
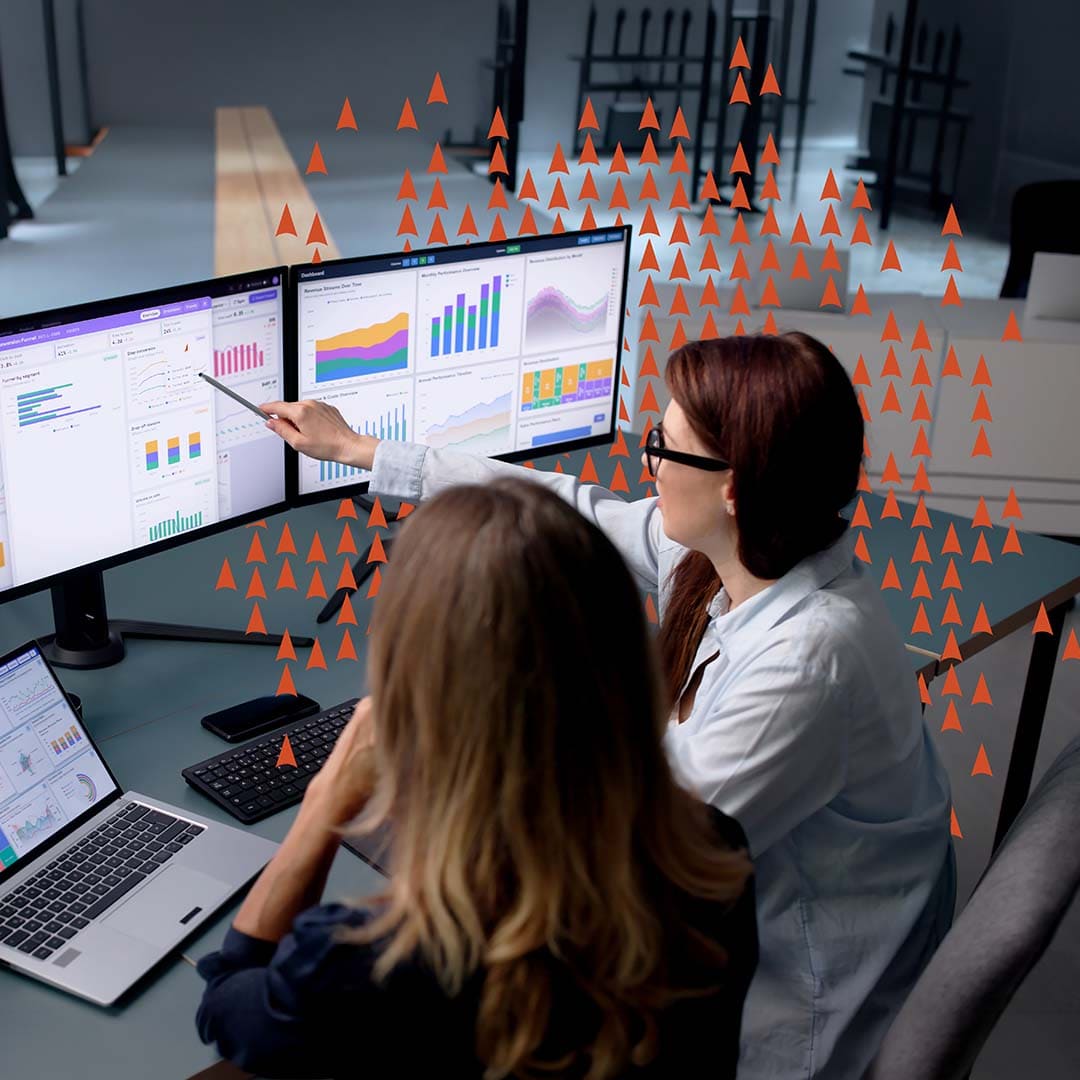
A US refrigeration equipment manufacturer manages temperature monitoring across more than 2,500 retail stores manually. The approach drove high equipment downtime, escalating maintenance costs, and left the client unable to control business-critical operations remotely. Altimetrik built a SaaS store monitoring platform with multi-site control, real-time temperature tracking, and detailed alarm/activity history. It added secure role-based remote diagnostics and CRM integration that auto-generates work orders from business rules, replacing manual monitoring with centralized, data-driven operations across the store estate.